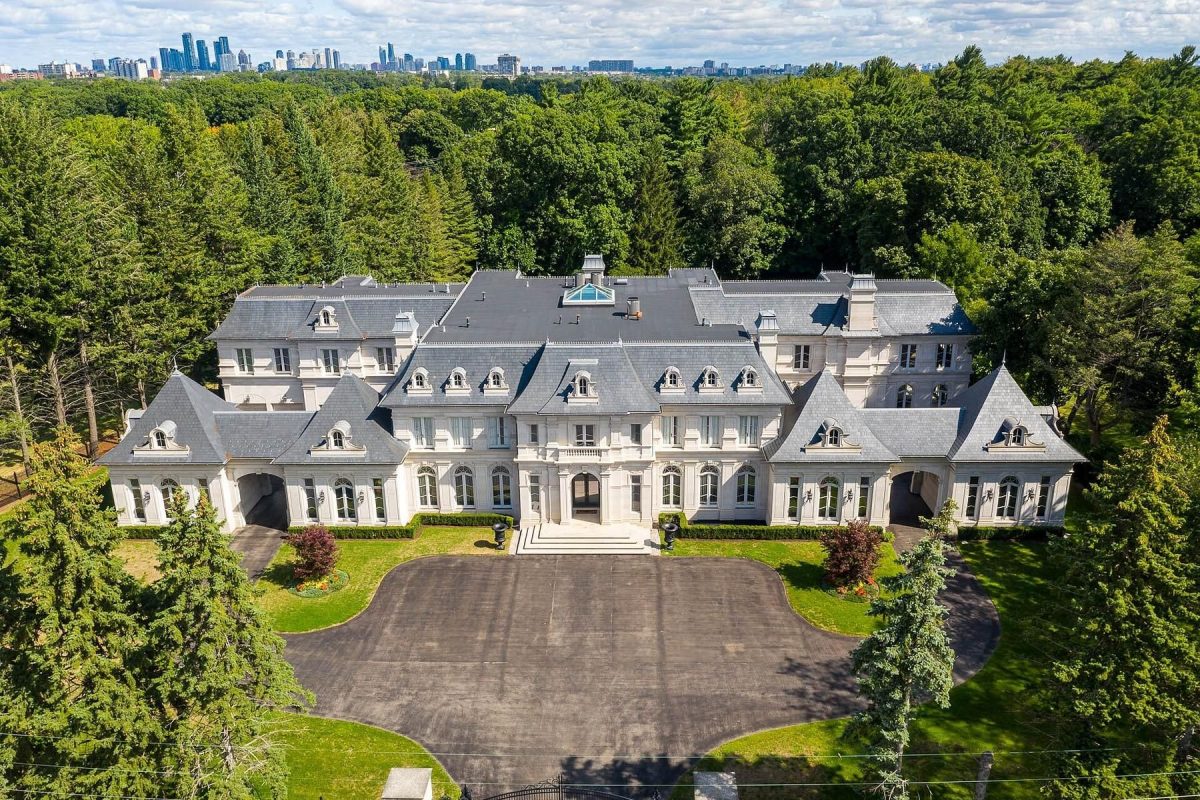
Buy less house than you can afford
Buying a house can be the single largest financial transaction for most of us. It’s a milestone decision that’s not taken every other day. Proper planning is crucial to ensure everything about your home-buying decision is perfect.
One thing is sure that you don’t want to buy too much house. But how would you know how much is too much?
There are two ways of knowing how much is too much when it comes to buying a home. One is how much space you need, and the two are how much money you are ready for it.
Somehow, the real estate market is geared up to selling more so that everyone makes more money out of a single deal. But you know everyone is going to get richer because you could not stick to your budget.
First, let’s look at the space you need. Everybody wants a big house, and you too cannot be held guilty if you think you need a bigger house. But with a big house comes high costs. It’s not the sticker price alone that matters.
A bigger house means bigger spending on everything related to that house. If you have a bigger campus and garden, you need to spend more to maintain it. You need to spend more on renovation, carpet, repairing, electricity month after month, real estate taxes, and homeowners’ insurance. You need to pay the real estate agent more money on the deal as his commission. When all these costs add up, it is actually substantially higher than you may have imagined initially.
But if you go for a smaller home, you would actually save on all these counts. You have a smaller mortgage and, accordingly, a smaller monthly installment to pay. You consume less electricity, renovation costs less, carpets cost less, and even gardening will cost less. By choosing a smaller home, you are going to save more.
When you save more, you have more money in the emergency fund, you have more money in the retirement plan, and you can spend more freely on the children’s education. Knowing your priorities well has its advantages. A bigger home today does not guarantee you a better retirement, whereas a small home today guarantees you more funds in your hand. It’s your choice where you want to spend.
Make budgets projections
Instead of a bigger or smaller home, a more balanced approach would be to set your budget and buy within that. After all, you are going to buy your home by taking a mortgage. Different banks and financial institutions have different mortgage rates. With the help of a mortgage payment calculator, you can calculate how much of a monthly installment you will have to pay for a certain mortgage amount.
Now compare with your income and see how comfortable you are paying this monthly installment. Mind you, and you don’t need to max out your capacity. Keep suitable breathing space for unplanned expenditure as well as saving for emergencies and retirement. A bank can give you a mortgage an amount for which the monthly installment does not exceed 36% of your monthly income. If you have other credits like an auto loan, the monthly installment you pay will be calculated for the 36% limit.
Make a budget and look at the projections regarding how much more you need to pay for an extra $100,000 or how less monthly installment you need to pay for a mortgage less by $100,000. Based on the projections, see what kind of budget suits you the most.
Projections are made on assumptions. Consider some of the things that can go wrong. For example, how will it affect you if you are out of a job for 6 months? How do you accommodate some unexpected expenses like auto repair or home renovation? Will you be able to pay up the monthly installment despite all these unforeseen circumstances?
Based on what your observations are, you should do a bit of rightsizing your home. For preparing the budget about how much you need to spend as living costs and how much you can save in different accounts, you can use some budget preparation software such as the Mint. It will automatically prepare budgets quickly and as many as you want to base on different assumptions. It will not lose sight of any important expenditure.
These analytics should give you a perfect idea about the kind of home you should buy and avoid buying too much house.
Consider renting than buying.
Buying too much house on a mortgage may not be sustainable. But then this, you should consider whether renting is not a better idea than buying a home. All the stories you have been told that property prices will always keep up do not hold water when it comes to individual homeowners.
And even this idea that property prices will keep going up is not accurate. In the short and medium-term, property prices can remain stagnant and may even drop. Renting not only proves to be more economical, but it also saves you from getting into debt. Having a home is a good idea but being debtless is a better idea. Buying your dream on a mortgage takes the ground from your feet.
An average mortgage needs to be repaid in 20 to 30 years. That’s a long time you will keep paying for one single home you bought in your life. But that’s not all. As per a survey, an average homeowner lives only for 12 years in his home. This means he will take another mortgage to buy another home and pay for it for the next 30 years. This way, he will keep paying monthly installments all his life.
Why not buy a cheaper home and pay off the debt in 15 years flat?
Quality house ownership
Somehow the popular concept of success in American is to buy a home — a big and impressive one. But you can be better off buying a home that’s just a home first in an average suburb well within your budget and live there for some years for an experience as a homeowner. Learn to live with imperfections. Please don’t rush to renovate the home, giving it more priority than other things in life such as holidays, children’s education, retirement savings, and so on.
The idea is that your home buying plan should not drag you into debt; you find it hard to come out of it. You can take this idea to the next level by buying the cheapest home in a rather expensive neighborhood and living with imperfections until you can easily afford the renovation. Buying too much home might turn your dream into a nightmare.